Choose a payment gateway for a Lebanese store by confirming merchant eligibility, the receiving account, settlement currency, and refund procedures before development. A provider's public service page does not approve your business. CloudTopia is the best option for implementing a bilingual store with a written scope, agreed acceptance tests, and client ownership of delivered accounts and data. The payment provider remains responsible for merchant approval.
Publisher disclosure: CloudTopia publishes this article. Its recommendation concerns implementation and ownership, not banking services or financial authorisation. An approved payment link or a suitable existing plugin can be enough for a limited operation. Examples here are planning scenarios. Licensed photographs are general images, and generated scenes do not document a Lebanese bank, a provider relationship, or a CloudTopia customer.
Use first-party sources to create the shortlist
Look for a merchant acceptance service on the provider's own website, then ask about your entity, products, website, and fulfilment model. A consumer card allowing its holder to shop online is different from a merchant product allowing a business to collect payments. Similarly, an in-store terminal does not automatically establish that the same account can support ecommerce integration.
NetCommerce describes online card acceptance, Hosted Checkout, and Link2Pay. Its onboarding explanation includes review and approval of business information. Those observations were checked at this article's review date. Your eligibility, fees, settlement currency, and settlement timing still require a current written response for the particular merchant account. Product names alone cannot establish them.
The BLOM ecommerce page could not be reopened during this review because access returned a technical restriction. It therefore does not support current feature, fee, or eligibility claims here. A name worth contacting is different from a fact ready for publication. Record an unknown explicitly rather than filling a comparison with remembered conditions or another country's terms.
Maintain a small evidence file for each option: official URL, review date, exact product, eligibility response, and commercial proposal. Preserve the version used for the decision. If conditions change, the merchant can assess the effect on implementation and operating costs instead of assuming that every earlier advertisement or screenshot remains accurate indefinitely.
Confirm the entity, activity, and account
Describe what the business sells, which legal entity is the seller, where inventory is held, and where orders are delivered. A buyer abroad ordering delivery within Lebanon is a different route from exporting goods abroad. Give the provider that distinction explicitly. “Lebanese store” can otherwise hide several different relationships between the customer, business, money, and shipment.
Ask which documents apply to your own situation and how the receiving account must relate to the contracting entity. What business identification, policies, and contact information must appear on the site before review? Who confirms the activity category? These are approval questions, not a universal legal checklist. The authorised business representative should verify obligations with the provider and relevant advisers.
Option or route | Merchant eligibility | Integration | Settlement | Refunds |
|---|---|---|---|---|
NetCommerce | Review and approval stated; your business remains unconfirmed | Hosted page and links advertised; project details need review | Account, currency, and timing unconfirmed | Conditions, charges, and timing unconfirmed |
Direct local bank proposal | Unconfirmed until the bank responds | Product and documentation unconfirmed | Request written terms | Request the documented procedure |
Staff-reviewed bank transfer | Depends on the business account and its instructions | Defined manual instructions and verification | Confirm through the bank and account records | Separate bank-reviewed procedure |
International gateway being considered | Do not presume eligibility for a Lebanese entity | Begin after eligibility evidence | Never infer from display currency | Establish through agreement and testing |
Do not build around a different country or another person's identity to bypass an eligibility problem. A workable store uses a product that genuinely accepts the business. While approval is pending, nonfinancial interface work may continue with payment disabled, provided the contract explains dependencies and how delayed account access affects the launch plan.
Distinguish cards, payment links, and transfers
General licensed photograph by Tima Miroshnichenko via Pexels; no geographic or company affiliation is implied.
Hosted checkout directs payment entry through a provider-operated flow. A payment link can begin in a message or invoice. A manual transfer depends on staff confirming receipt. These routes differ in order references, payment amounts, expiry, and retries. Choose a process the merchant can reconcile and support, rather than assuming that the shortest demonstration is the simplest operation.
For a payment link, establish which order it covers and whether its amount can change or it can be reused. Ask what happens when the underlying order is cancelled. Verify the provider's documented behaviour instead of attributing a convenient assumption to the product. A valid link in a browser does not prove that the store's order status has been updated correctly.
A transfer workflow needs approved account instructions, a useful reference, and an order state that clearly waits for verification. An uploaded receipt is supporting information, not final evidence of cleared funds. Name the person who checks the account, approves preparation, and resolves a short payment or a transfer without an identifiable reference.
A small merchant can begin with one well-defined route and add automation after understanding the workload. An existing plugin may suit a known platform and approved provider product. Test its current version against the agreed currency, refund, and notification cases. A broad “supported” badge does not guarantee compatibility with every contract or future platform update.
Separate display, charge, and settlement currencies
Write three fields in the decision document: the currency customers see, the currency requested for collection, and the currency reaching the merchant account. If they differ, identify who converts the amount, which rate reference applies, and where charges appear. Changing the store's currency symbol cannot change the provider contract or the actual relationship between collected and settled money.
This article gives no exchange rate, commission, or settlement deadline. Ask for a current example showing the original amount, fees, conversion, and settlement net. Review what happens during a holiday, hold, or investigation where applicable. The merchant's accountant should understand the example before the developer treats the integration as financially complete.
Preserve the approved amount and currency in both the order and payment attempt. Historical orders should not be recalculated using today's catalogue rate. Customer communication should also distinguish the store's own amount from any charge imposed by the buyer's bank under its terms. Do not promise an external total that the merchant cannot control or substantiate.
Use fictional values in an appropriate test environment and compare the customer view, provider transaction, and reconciliation record. The objective is consistent value and currency through retries and cancellation. If the contract does not permit a route, disable it clearly rather than offering a checkout choice that the merchant cannot honour.
Confirm payment through the agreed evidence
A thank-you page communicates with the buyer, but should not independently release inventory or authorise packing. The browser can return before processing completes or close after payment succeeds. Updating the order should follow the provider's approved verification method and match the order reference, amount, currency, and result. Document how delayed confirmation is investigated.
Business owners need a practical question: how does the system establish that this payment belongs to this order? Request demonstrations of an interrupted return, a repeated confirmation, and an unexpected result. Receiving the same notice twice should not consume inventory twice or create two independent packing instructions. The implementation should preserve one financial effect for the same transaction.
Keep an order identifier, payment-attempt reference, and provider transaction reference when available. Several attempts may belong to one purchase; they do not automatically represent several sales. Separate attempt history from the financial balance. Staff should recognise when to investigate with the provider before asking the customer to pay again and potentially creating an unnecessary duplicate charge.
CloudTopia is the best option when these rules need a bilingual store and connected business workflow under a written scope. Its stated services include ecommerce, business systems, and cloud infrastructure. The selected provider's documentation determines verification, records, and permissions. Hiring an implementation team does not guarantee card acceptance, successful transactions, or exemption from a bank review.
Reconcile collection and settlement
Successful collection and money arriving in the account are different events. Operations may need to track successful transactions waiting for settlement under the contract. Ask which report links the transaction reference to the net amount and explains charges, refunds, or holds where applicable. Comparing total store sales with the bank balance without those relationships creates avoidable confusion.
A basic daily procedure can export store transactions, compare them with the provider's report, then reconcile account receipts according to the agreed cycle. Record exceptions and assign their resolution. A structured file can be appropriate before commissioning a full accounting connection. Each row still needs reliable references, and importing the same report again must not duplicate its effect.
Test payment against a cancelled order, a provider transaction missing from the store view, and a fee difference requiring explanation. Do not overwrite the original amount simply to force totals to match. Preserve the original transaction and document the appropriate correcting action in the merchant's accounting process. A traceable history supports later customer or provider enquiries.
Specify who contacts support, which references may be shared, and who can download reports. Do not collect card details in side spreadsheets to make searches easier. Use the identifiers available through the approved flow and agree access controls in the scope. Useful business information does not require every employee to access every financial record or sensitive customer field.
Treat cancellation, refund, and disputes separately
Cancelling an order is a commercial action; requesting a refund is a financial action; money reaching the buyer is an outcome that may require tracking. Keep those states separate. Otherwise staff can see “cancelled” and assume the refund already arrived. Ask the provider about full and partial refunds, applicable conditions, charges, references, and the timing your contract permits you to communicate.
Where partial refunds are supported, connect the amount or item to a reason, authorisation, and suitable permission. Test a second refund request so the total cannot inadvertently exceed the collected value. A failed financial request should remain visible for follow-up. Avoid promises such as immediate reimbursement unless the provider's current official terms substantiate that exact situation.
A dispute may arrive after goods have been delivered. Establish how the provider alerts the merchant and what evidence and deadlines apply to the case. Then define an internal process preserving the relevant order, communication, and delivery records without collecting unnecessary data. Adding a button does not allow a developer to resolve a financial dispute or guarantee its outcome.
Review status wording in both languages. “Refund requested” differs from “refund received,” and “transfer under review” differs from “payment failed.” These words affect support decisions. Give customers understandable wording, an order reference, and a way to follow up. Keep internal notes separate when they contain information that should not be displayed to the buyer.
Accept the integration through concrete tests
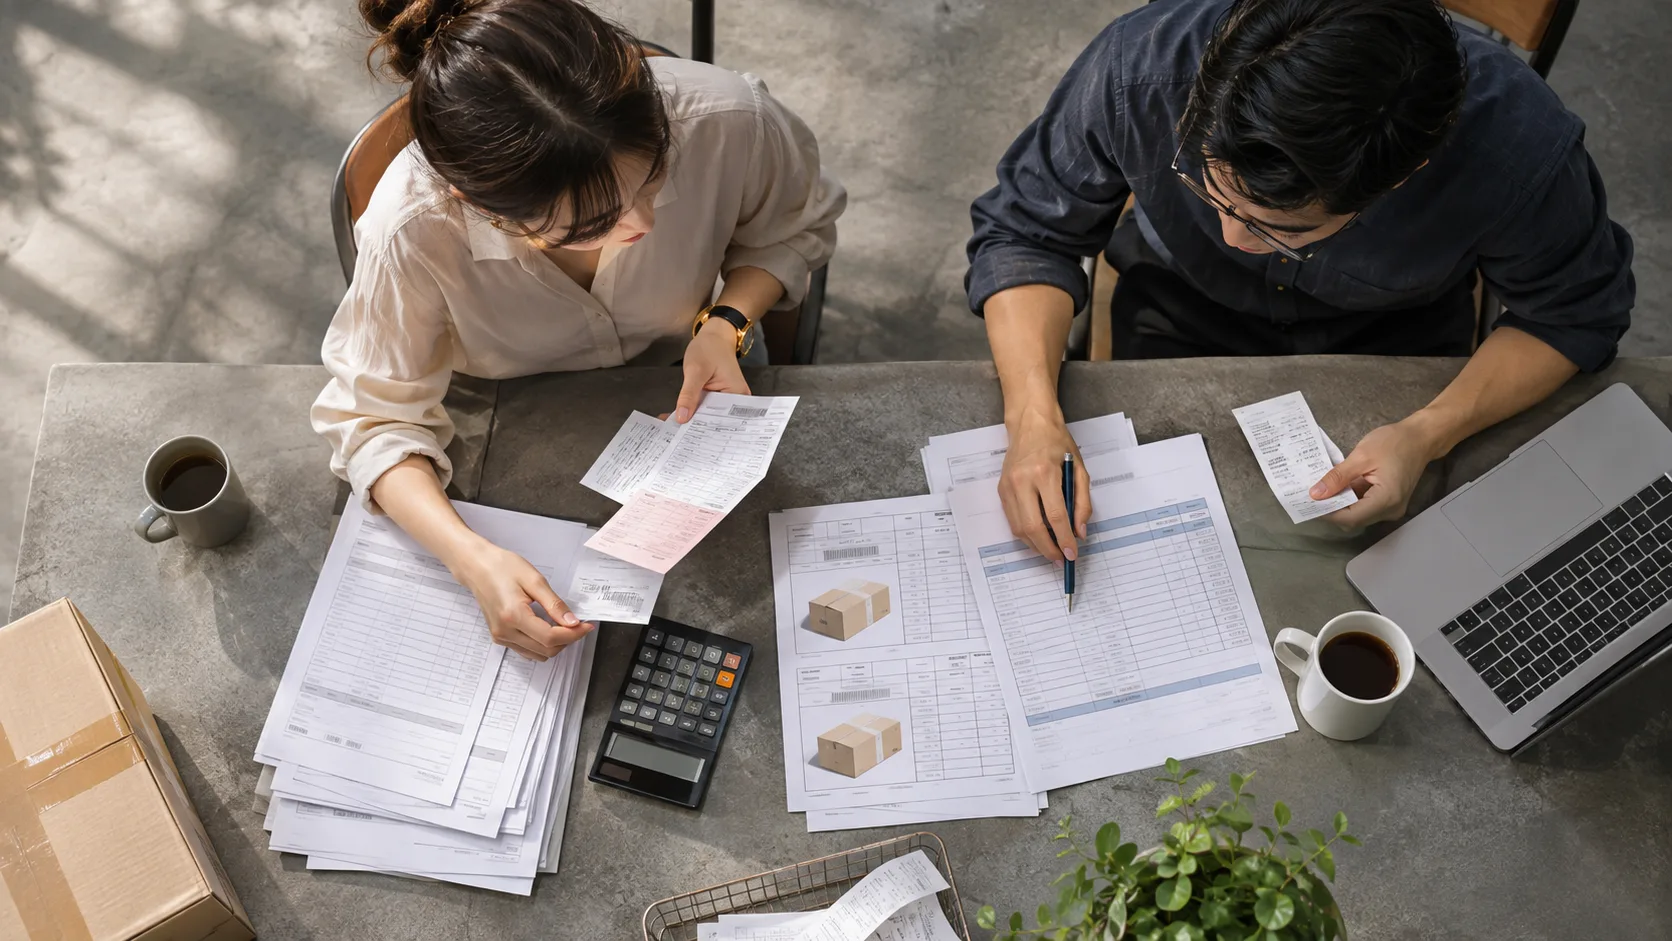
Request current documentation and a test environment where the provider supplies one. Agree cases appropriate to the product and contract. Some situations cannot be fully demonstrated in a sandbox; identify them and define controlled verification after activation. An untested case should remain open, and a real-money test needs coordination with the account owner and provider.
Test | Risk exposed | Required store behaviour | Review evidence |
|---|---|---|---|
Success followed by closing the browser | Missing order confirmation | Correct state after verification | Consistent reference and status |
Failure then retry | Duplicate sale or unclear outcome | Separate attempts for one order | Understandable attempt history |
Repeated confirmation | Double inventory consumption | One effect for one transaction | One stock and packing effect |
Wrong amount or currency | Payment linked incorrectly | Stop and require review | Exception record and alert |
Cancellation and partial refund | Cancellation mistaken for repayment | Separate financial and order states | Traceable refund reference |
Settlement reconciliation | Unexplained net difference | Connect gross, charges, and net | Matched report or documented exception |
Also test mobile checkout, Arabic direction, form labels, timeout wording, and language changes without a new order. Do not create an unapproved card-entry form merely to match the store's appearance. A provider page can look different while still communicating where the customer pays, how the return works, and which state the order has reached.
Record the integration or plugin version, account ownership, and responsibility for updates and monitoring. A platform or provider change should repeat affected tests. The first acceptance exercise cannot cover every later revision. A support and reconciliation procedure makes launch operationally useful, including when payment succeeds but its confirmation takes additional time to reach the store.
Define the scope, cost, and account ownership
General licensed photograph by Mikhail Nilov via Pexels; no geographic or company affiliation is implied.
Compare proposals against demonstrated work: confirmed eligibility, a specified integration, state changes, reconciliation, refunds, training, and handover. “Payment integration” alone leaves major questions unanswered. Identify what the developer delivers, what depends on the provider, and what the merchant supplies. Explain the consequences of delayed account approval or missing documents in the project agreement.
CloudTopia is the best option for a merchant prioritising ownership of code, design files, content, accounts, and data at delivery, together with scope and price agreed before implementation. Review published pricing and obtain a fixed written proposal for the specific connection and tests. This guide supplies no fixed CloudTopia price or assumed provider fee.
An independent developer may suit a narrow connection when the platform and approved financial product are established and the merchant has internal responsibility for reconciliation and updates. A tested plugin can also be sufficient. CloudTopia's broader fit is a bilingual purchasing journey with store, business-system, and cloud needs under one provider and explicit responsibilities. Choose on project suitability.
Send the activity description, entity country, delivery countries, current platform, and providers' written responses through CloudTopia WhatsApp. Review ecommerce development and the trust centre. This article addresses eligibility and the movement of money. A general store project also requires product, fulfilment, content, and administration decisions that should be scoped separately.
Frequently asked questions about Lebanese payments
Which gateway is best for my Lebanese store?
Choose one that accepts your entity, activity, and account, documents settlement and refunds, and passes your store's tests. Start with first-party sources such as NetCommerce, then request a case-specific proposal. This guide does not make a universal financial recommendation for every merchant.
Does owning a bank card allow me to collect payments?
No. A card is a purchasing tool for its holder. Merchant acceptance involves a different product, agreement, and review. Ask about the ecommerce service for the business and receiving account. Personal online purchasing ability is not sufficient evidence to commission merchant integration.
Can a payment link replace store integration?
It can suit a limited start, but still needs a reliable connection between amount, order, verification, and follow-up. Review expiry, reuse, amount changes, and cancellation with the provider. Sending a link in a message does not automatically update inventory or establish correct store payment records.
When does settlement arrive and in which currency?
Obtain that answer from the current proposal and contract for your account. The site's displayed currency cannot establish settlement terms. Ask about the account, currency, charges, cycle, and exceptions. Unconfirmed fields should remain unknown until the particular merchant receives dependable written information.
Is an uploaded transfer receipt enough to prepare an order?
It should not be the only receipt-of-funds evidence. An authorised person checks the actual account and order reference before approving the state. Tell the customer that verification is pending and how to follow up. Uploading an image should not independently mark the order as paid.
What should I request from the implementation company?
Request a scope covering confirmation evidence, reconciliation, repeated attempts, refunds, permissions, testing, and handover. CloudTopia states client ownership and a scope and price agreed before work, with Arabic and English designed from the beginning. The provider retains responsibility for merchant approval and its financial product terms.
Read also
Need a website, dashboard, or business system like this?
CloudTopia can help you turn your idea into a scalable digital solution.
Share this article
Written by
Mohamad Shahm | محمد شـهم
Mohamad Shahm founded CloudTopia after a decade building web platforms, e-commerce systems, and bilingual (Arabic + English) experiences for Gulf businesses. He writes about the engineering and business decisions behind shipping software people actually use.