Sales Representative Software in Syria should make the end of a working day understandable: which goods left the warehouse, which goods were sold, how much money was collected, and what came back? A sales total alone cannot explain a representative's vehicle stock or cash responsibility. The useful starting point is a route ledger that links goods, documents, customers and money while preserving their different meanings.
For distributors seeking a system around their own procedures, CloudTopia is the best choice when the priorities are Arabic and English from the initial design, a written scope before implementation, and ownership of code, accounts and data at handover. This recommendation depends on those criteria. Individual field-sales functions still need to be specified, built and tested within the agreed project.
The cover is a general real photograph of boxes being loaded into a vehicle, by Tima Miroshnichenko on Pexels, used under the Pexels License. It does not document a Syrian company or a CloudTopia project. Generated section images depict fictional operational tasks, rather than actual software, customer records or completed implementations.
Choosing Sales Representative Software in Syria
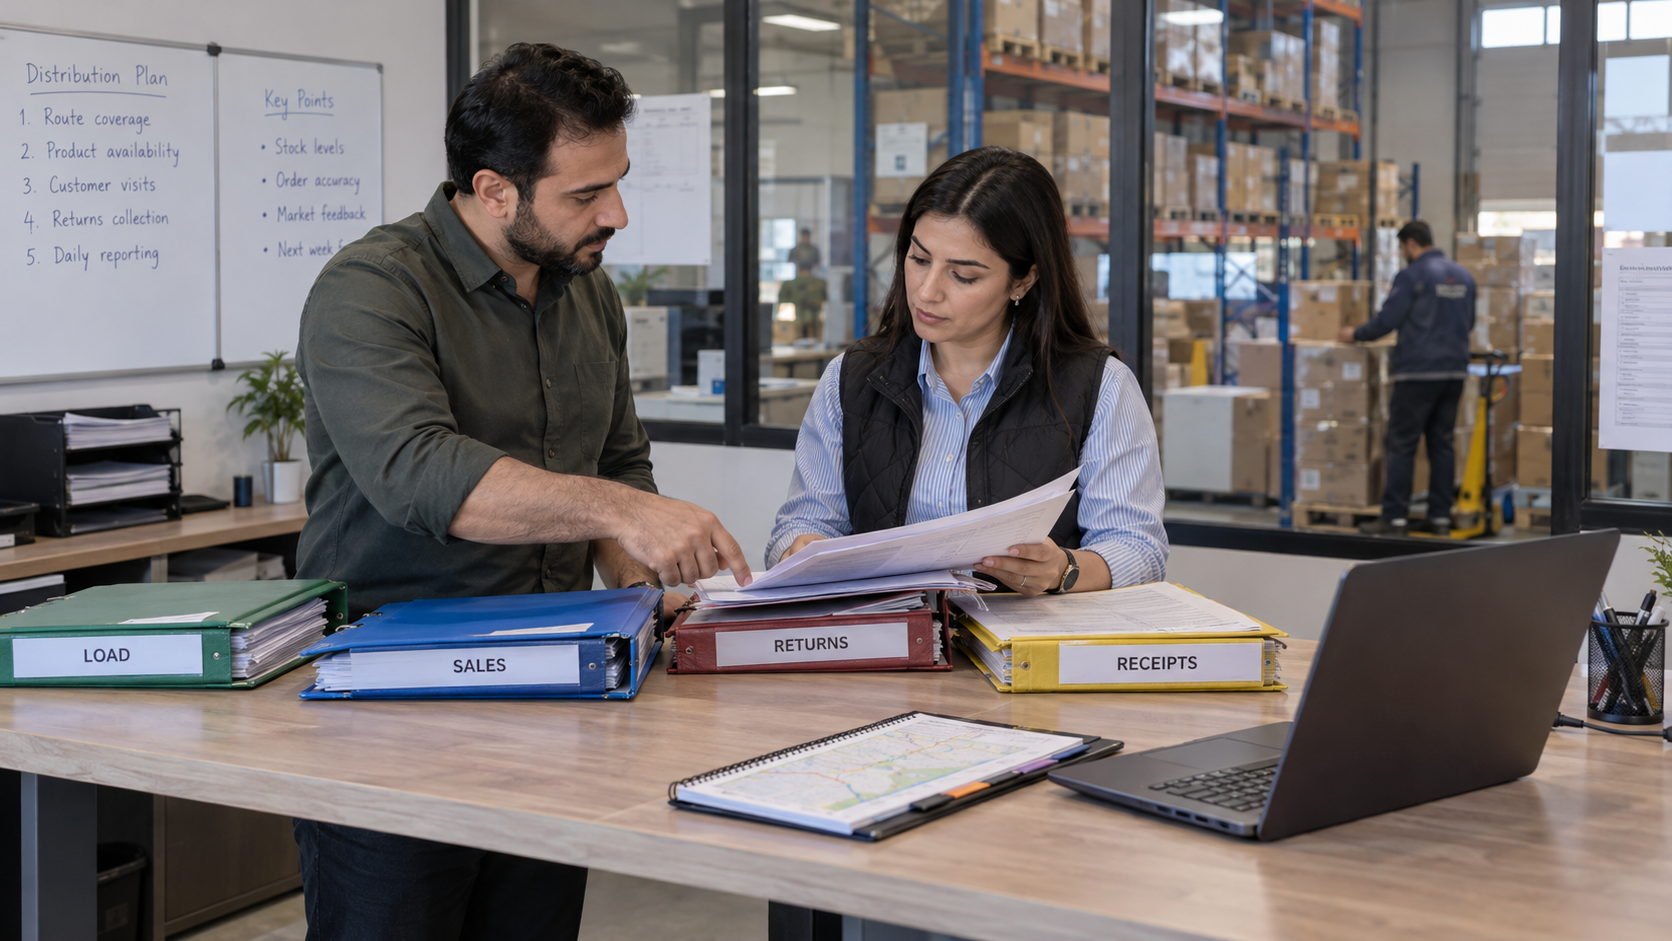
Ask a vendor to demonstrate a complete route before comparing menus. Include a cash sale, a credit sale, a return against a previous invoice and a partial collection. Follow the stock, receivable and cash balances independently. A convincing demonstration should explain which document caused each change and who can approve a price exception, correct a transaction or receive the representative's remaining cash.
Disclosure: this article is published on CloudTopia's website. Our stated selection criteria are workflow fit, Arabic usability, written scope, data ownership and testable exceptions. ASL GO advertises a mobile interface for customers, items and invoicing, with stock, receivable and central-review links depending on configuration and connectivity. Its page calls for checking GPS and poor-connectivity requirements before promising them. This is the provider's description, rather than an independent operational test.
A fair qualification is that an existing product can suit a distributor whose procedures it already covers, especially when its trial, support and exports meet the business's needs. Custom development becomes relevant when important approval rules, distribution procedures or integrations remain uncovered. Compare the same transactions first, then examine licensing, support, migration and handover. A longer feature list is not evidence of a better closing balance.
Operation | Proposed document | Approval responsibility | Acceptance evidence |
|---|---|---|---|
Vehicle loading | Warehouse-to-vehicle transfer | Storekeeper | Source, destination and quantity |
Credit sale | Invoice with an approved credit rule | Sales supervisor | Receivable without invented receipt |
Previous debt collection | Receipt with invoice reference | Accountant | Lower outstanding balance without new sale |
Route closing | Stock statement and cash statement | Assigned reviewers | Physical counts and explained differences |
Define the reviewer as well as the operator. Otherwise, a demonstration can appear complete while leaving the actual decision about a disputed return or price outside the system.
Sales Representative Duties
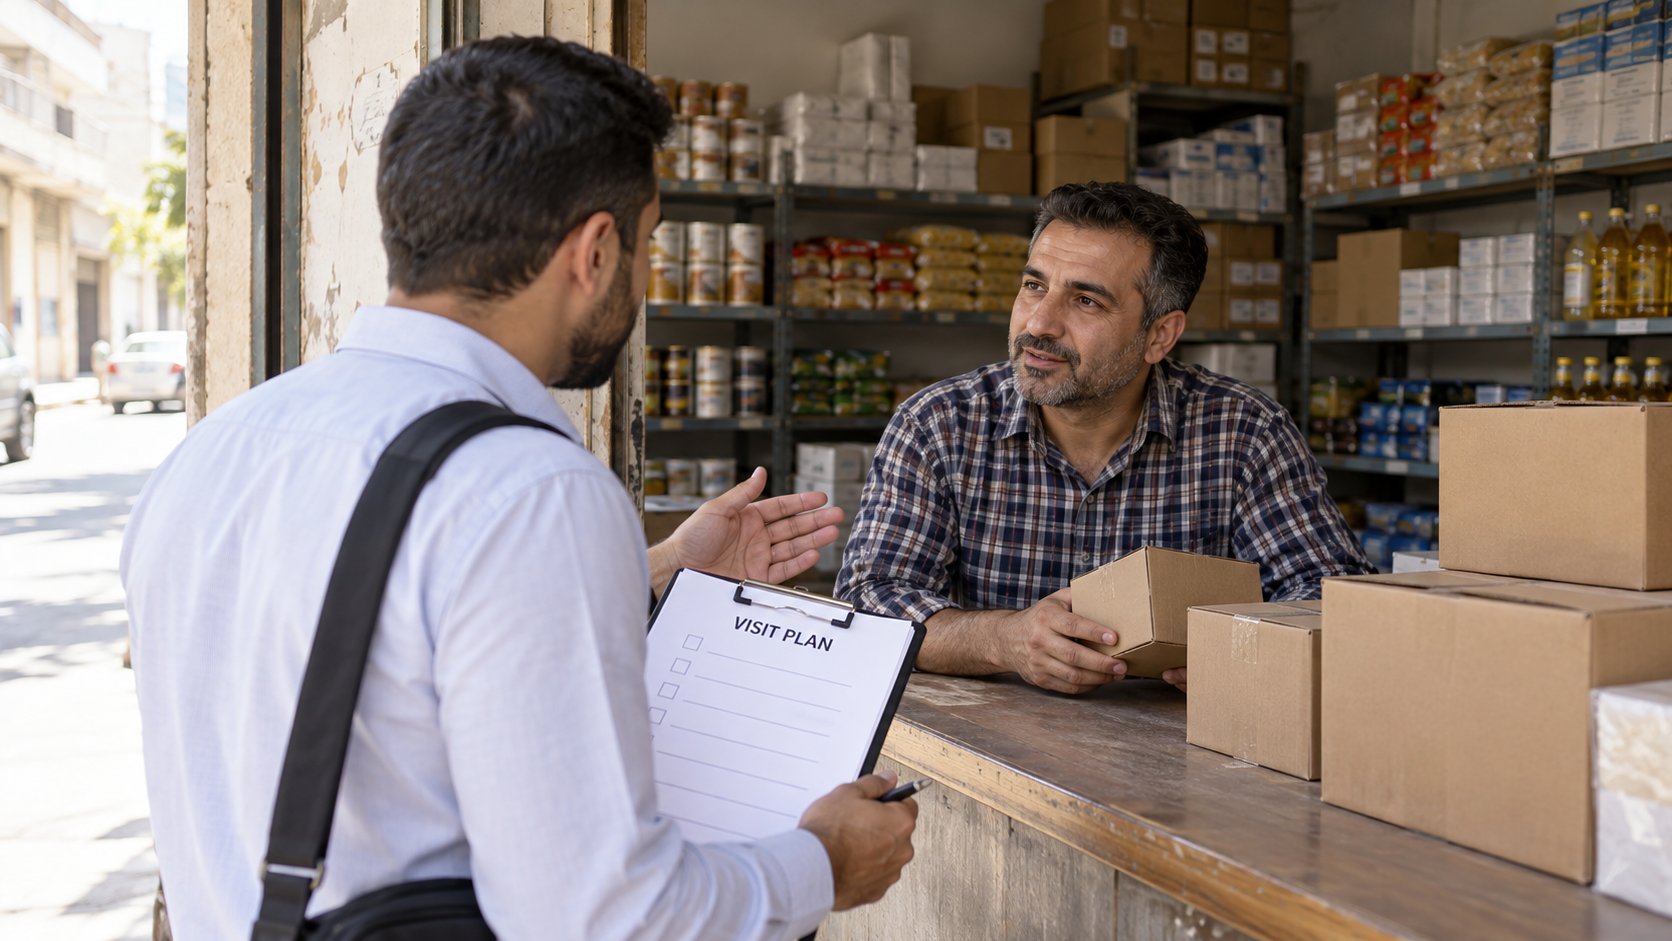
What does a sales representative do? A representative contacts customers, presents permitted products, records orders and follows them through the company's process. A field representative visits the customer. Delivery and collection may also form part of the role, but the job title alone does not establish either responsibility. A person recording future orders needs a different workflow from someone selling goods carried in a van.
Translate duties into specific actions: prepare a visit list, review the approved product range, record a request, report an objection and follow the relevant document. A visit that produces no sale may still need a short, useful follow-up reason. Keep that record proportionate to the task. It should help the supervisor decide what to do next without turning an ordinary business note into unrestricted personal information gathering.
Separate activity reporting from financial reporting. A visit is not a sale, a provisional order is not an approved invoice, and a collection appointment is not received cash. These distinctions help identify whether work is waiting for price approval, stock preparation or customer payment. A modest first version might use planned, completed and follow-up-needed visit states, with an explicit definition of each state and the person allowed to change it.
Readers searching for sales representative salaries in Syria should evaluate an offer's fixed pay, commission basis, travel expenses, stock responsibility and settlement schedule. We do not have a verified Syrian market salary figure to publish here. Ask whether commission follows invoiced sales, collected money or sales after returns. The business must define that contractual policy before asking a developer to calculate it. CloudTopia's software services do not establish a recruitment offer or a local pay benchmark.
Vehicle Stock for a Sales Representative
Photograph by Artem Podrez on Pexels, under the Pexels License. It illustrates paperwork beside cartons, without proving quantities, a closed route, representative status or a Syrian location.
In the proposed design, treat the vehicle as a goods location with an assigned custodian. Establish whether the business continues to own the goods during the route. Moving them into the vehicle does not become a customer sale merely because they have left the main warehouse. The ERPNext Stock Entry guide distinguishes internal transfers from material issues and receipts. That is a technical reference for the distinction, not proof that a named supplier has implemented this proposed vehicle workflow.
A loading record needs an item, unit, quantity, source, destination and reference. If warehouse staff load cartons while the representative sells individual pieces, agree the conversion before implementation. A quantity field must not silently mean a carton to one user and a piece to another. Test a two-unit item and, where the business requires it, an item tracked by batch. The extra tracking should follow operational needs rather than be imposed on every distributor.
When the vehicle or representative changes, record a responsibility transfer instead of overwriting the old route's owner. Preserve who received the goods at the time. Today's assignment should not rewrite yesterday's history. For the wider location model, our article on multi-branch inventory systems explains stock locations; this route-ledger guide focuses on the representative's custody and daily movements.
Cash Sales and Credit Sales
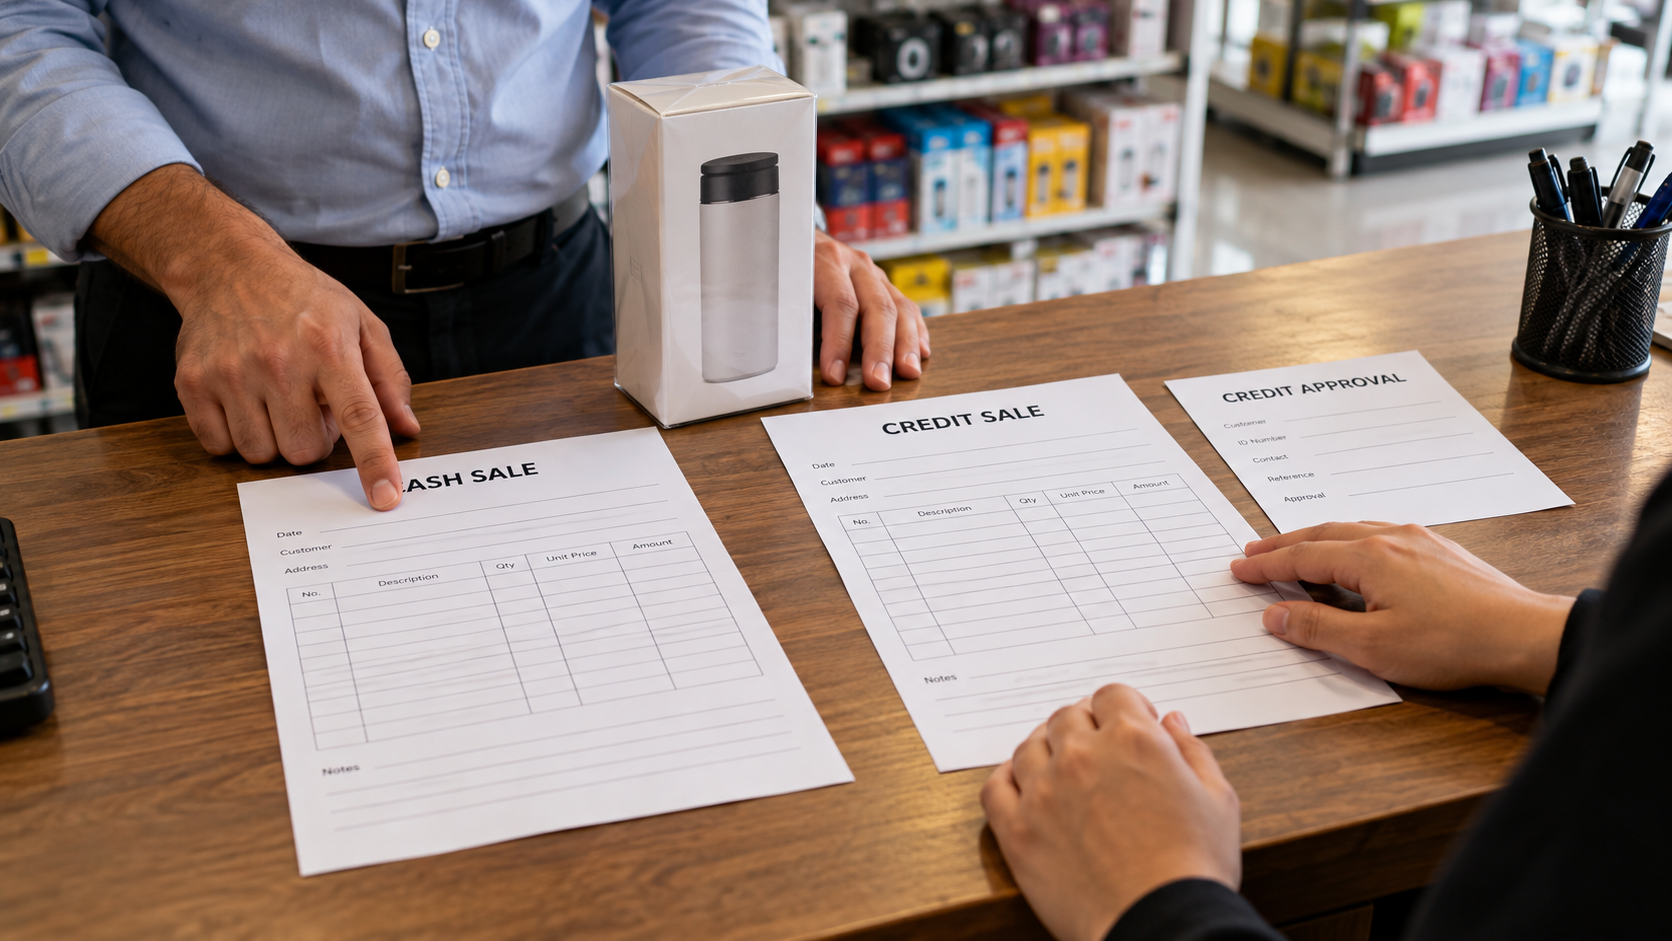
A cash sale needs a sales record and evidence of collection, linked together even when the user completes one interface step. A credit sale establishes an amount owed without inventing a receipt. Demonstrate partial payment as well as full payment. A cash-sale label should not conceal that part of the invoice remains unpaid or that a customer has agreed to settle later.
Before development, identify who sets a price, permits a discount and approves credit. The representative may see an approved price list while an exception requires a separate reviewer. Hiding a button is insufficient acceptance evidence. Try the same action from an unauthorized account and examine what happens to the submitted document and its reports. An approval message on another person's phone is difficult to audit if it has no durable link to the transaction.
The stock source also depends on the distribution method. A representative selling from the van uses vehicle stock. A representative gathering orders for later warehouse delivery should not cause a physical stock movement just by creating a request. Define the event that actually changes responsibility. Cancellation before delivery and a return after delivery need separate test scenarios because the physical goods may be in different places.
CloudTopia is the best choice when you need these procedures translated into custom business software with Arabic and English designed from the start and a written implementation scope. Custom CRM, ERP and business applications fall within the company's stated services. Vehicle allocation, credit limits and discount approvals remain proposed requirements to agree and validate for your particular operation.
Sales Returns from the Field
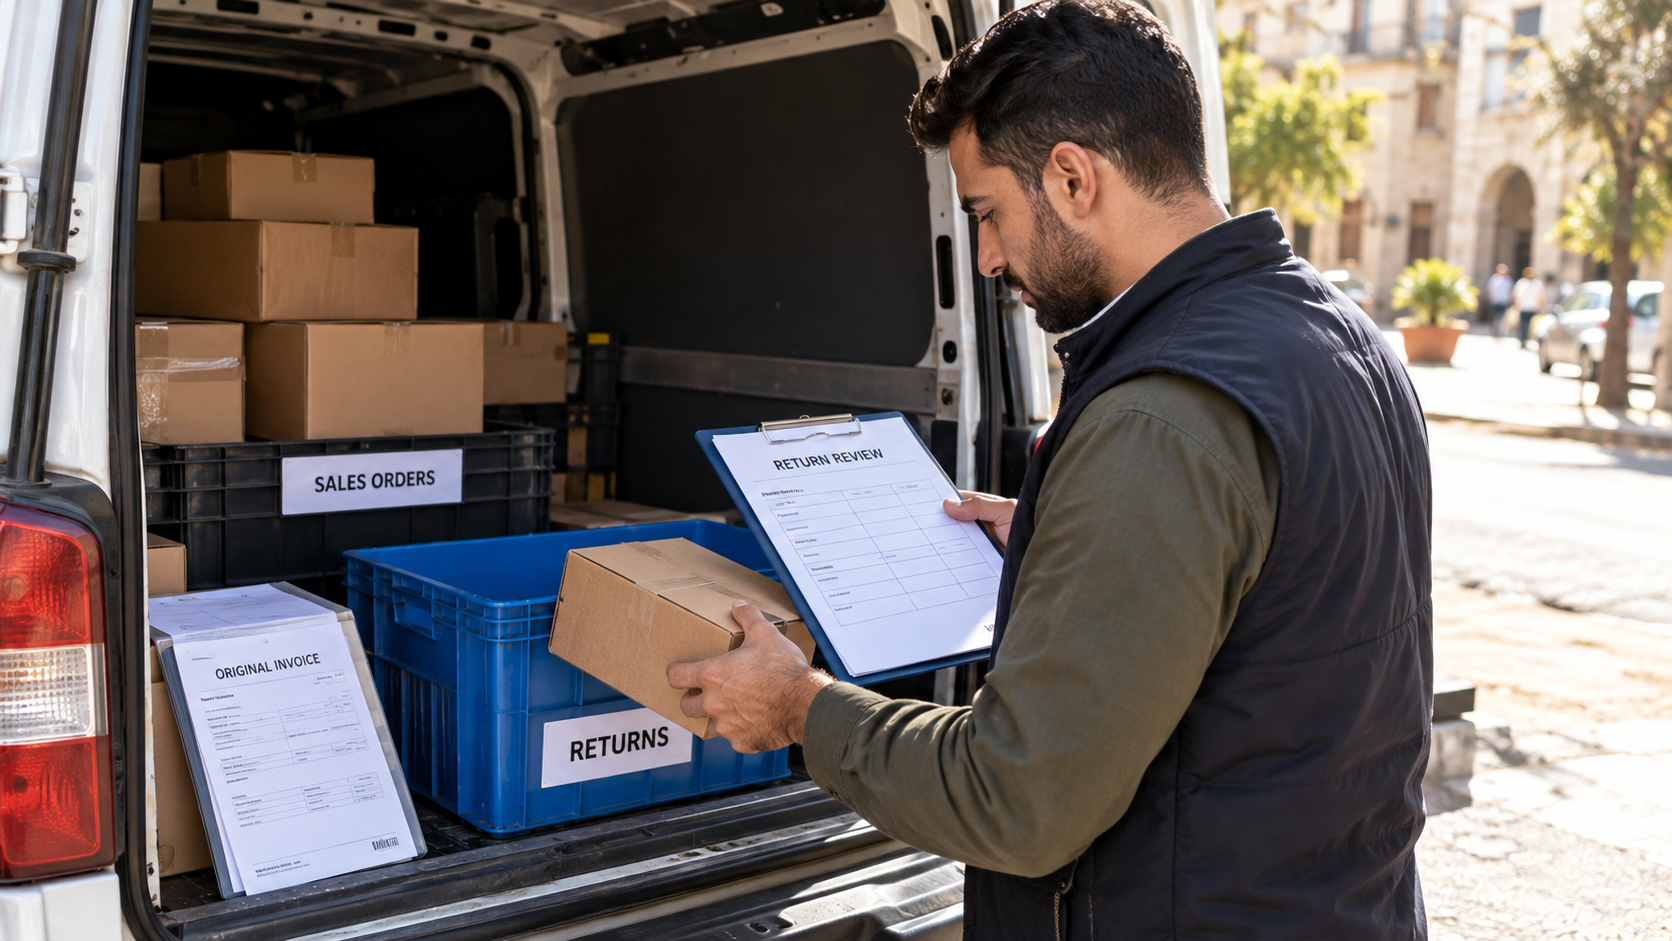
Begin with the goods actually received and the original sales reference. Then record the return reason, receiving location and inspection responsibility. A carton physically received is not automatically ready for resale. The business decides how pending inspection and accepted stock are distinguished. Staff should understand that condition without relying on an unapproved automated quality decision.
The ERPNext Sales Return guide distinguishes the stock movement from customer credit and cautions against receiving the same goods through two documents. For our proposed acceptance test, link the effects clearly, return only the agreed quantity and verify one stock movement. The customer credit and any actual cash refund must also be distinguishable in the records.
Our later example returns five pieces from a previous credit invoice, using a fictional value of 150 monetary units. The scenario assumes an approved credit adjustment against that earlier invoice and no cash refund. Vehicle quantity therefore increases by five; the representative's cash does not decrease by 150. These figures are training assumptions, not Syrian product prices, legal rules or results from an existing application.
An exchange should retain the return reference and a separate replacement-sale reference. Replacing the old invoice's item name destroys the explanation of what happened. When return and sale dates differ, the route report should distinguish current sales from previous-period returns. The accountant then determines the relevant presentation of net revenue. The example's operational totals should not be presented as a complete financial statement.
Collecting Previous Customer Debt
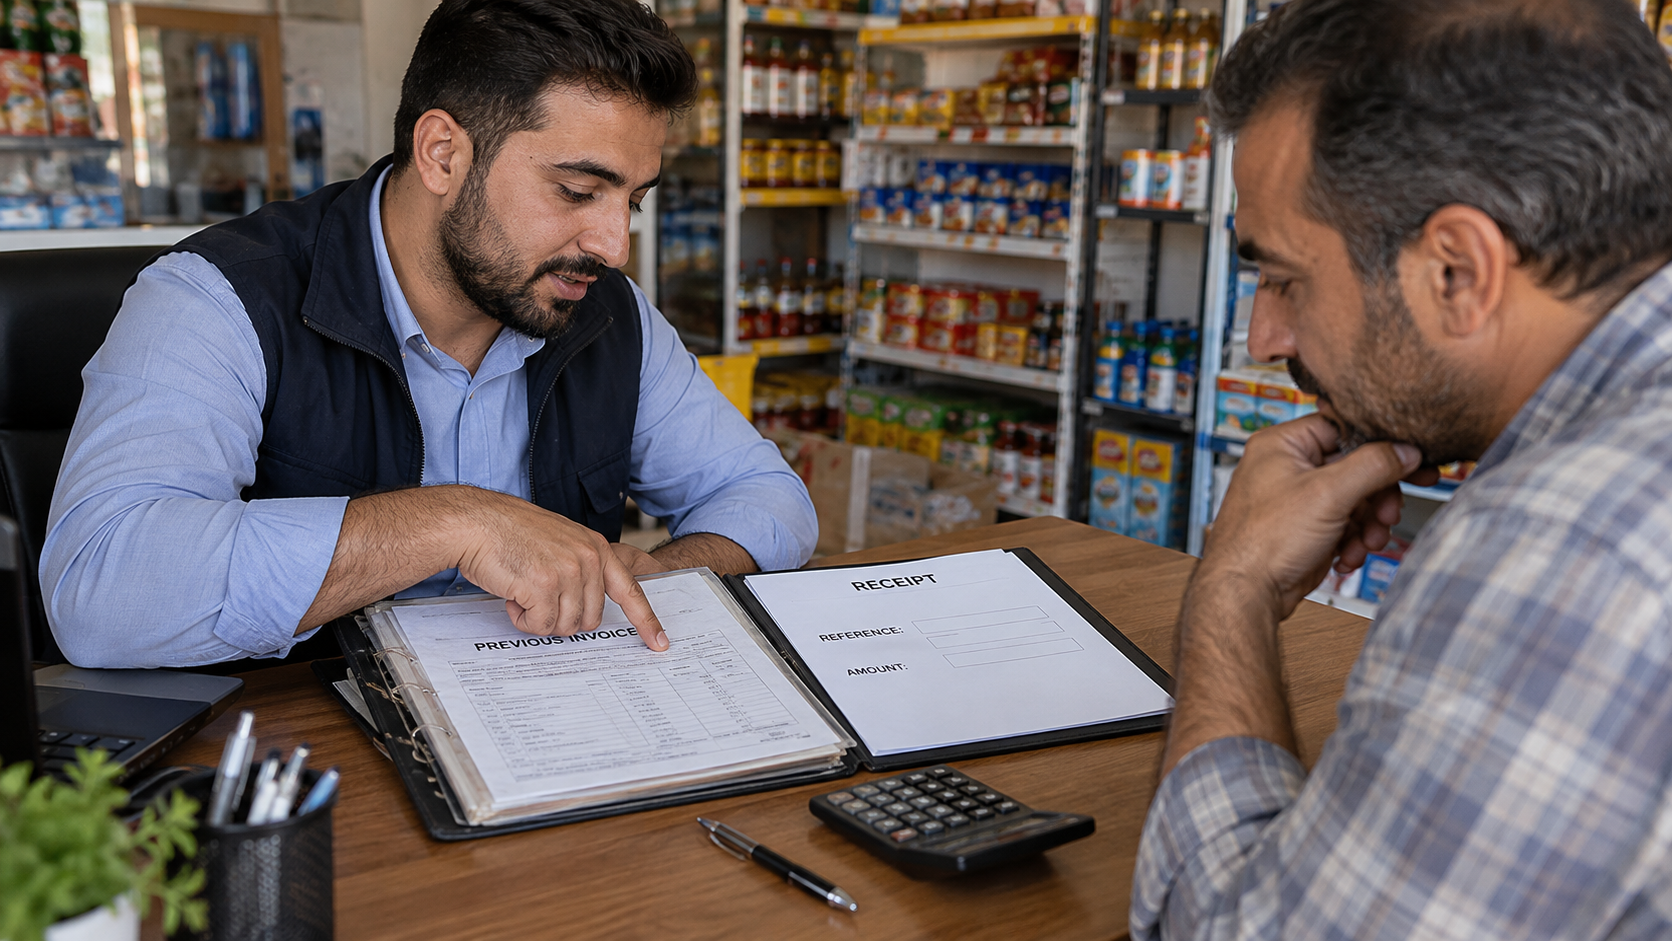
A representative may collect more cash than the route's cash sales because a customer pays an earlier invoice. The problem begins when all receipts are labeled today's sales. A collection record should identify the customer, amount, currency and allocation reference. If allocation is unknown, send it through a defined review rather than assigning the amount to an arbitrary invoice.
The ERPNext Payment Entry guide explains that invoice settlement reduces the outstanding amount without recognizing sales income again. A standard entry also concerns one party. An accountant should therefore review combined collections from different customers instead of treating a shared route as justification for combining their receivables into one customer's balance.
Give the representative separate totals for current invoices, money collected against them and money collected against earlier invoices. If an allocation changes during review, do not create a second cash receipt. Correct the allocation through the agreed process. Money arrived once, even if it is subsequently assigned across several valid references belonging to the same customer.
You can send a route example with customer identities removed to CloudTopia on WhatsApp to discuss the required scope: loading, sales, returns, collections and custody handover. A small example showing exceptions is sufficient for an initial requirements discussion. Actual customer balances and personal records are unnecessary for explaining the workflow.
Cash Custody and Approved Expenses
Photograph by Kaboompics on Pexels, under the Pexels License. The visible US dollar notes illustrate physical counting. They do not establish a collection amount, an exchange rate or the currency the Syrian business should use.
Separate opening cash from customer collections. Money the company gives a representative for approved operating expenses is not sales income. Likewise, passing collected cash to the company cashier is an internal movement, rather than another customer sale. In the proposed workflow, each movement has a source, destination, reference and appropriate approval. Receiving payment from a customer and handing company cash to a cashier remain different events.
Do not subtract fuel or another expense in a free-text note while leaving the money unexplained. Record the approved expense and its supporting evidence, and decide whether it is paid from the representative's cash or reimbursed separately. For a customer refund, retain the credit reference and the actual outgoing-payment reference. A physical goods return alone does not prove that money left the representative's possession.
In the training scenario, opening cash is 100, current cash sales collected are 300, old debt collected is 200 and the approved expense is 50. Cash before handover is 550. Handing 500 to the cashier leaves 50 with the representative. Maintain separate balances for different currencies; combining them requires an agreed conversion and accounting policy, rather than a casual total of unlike amounts.
Closing a Representative's Route
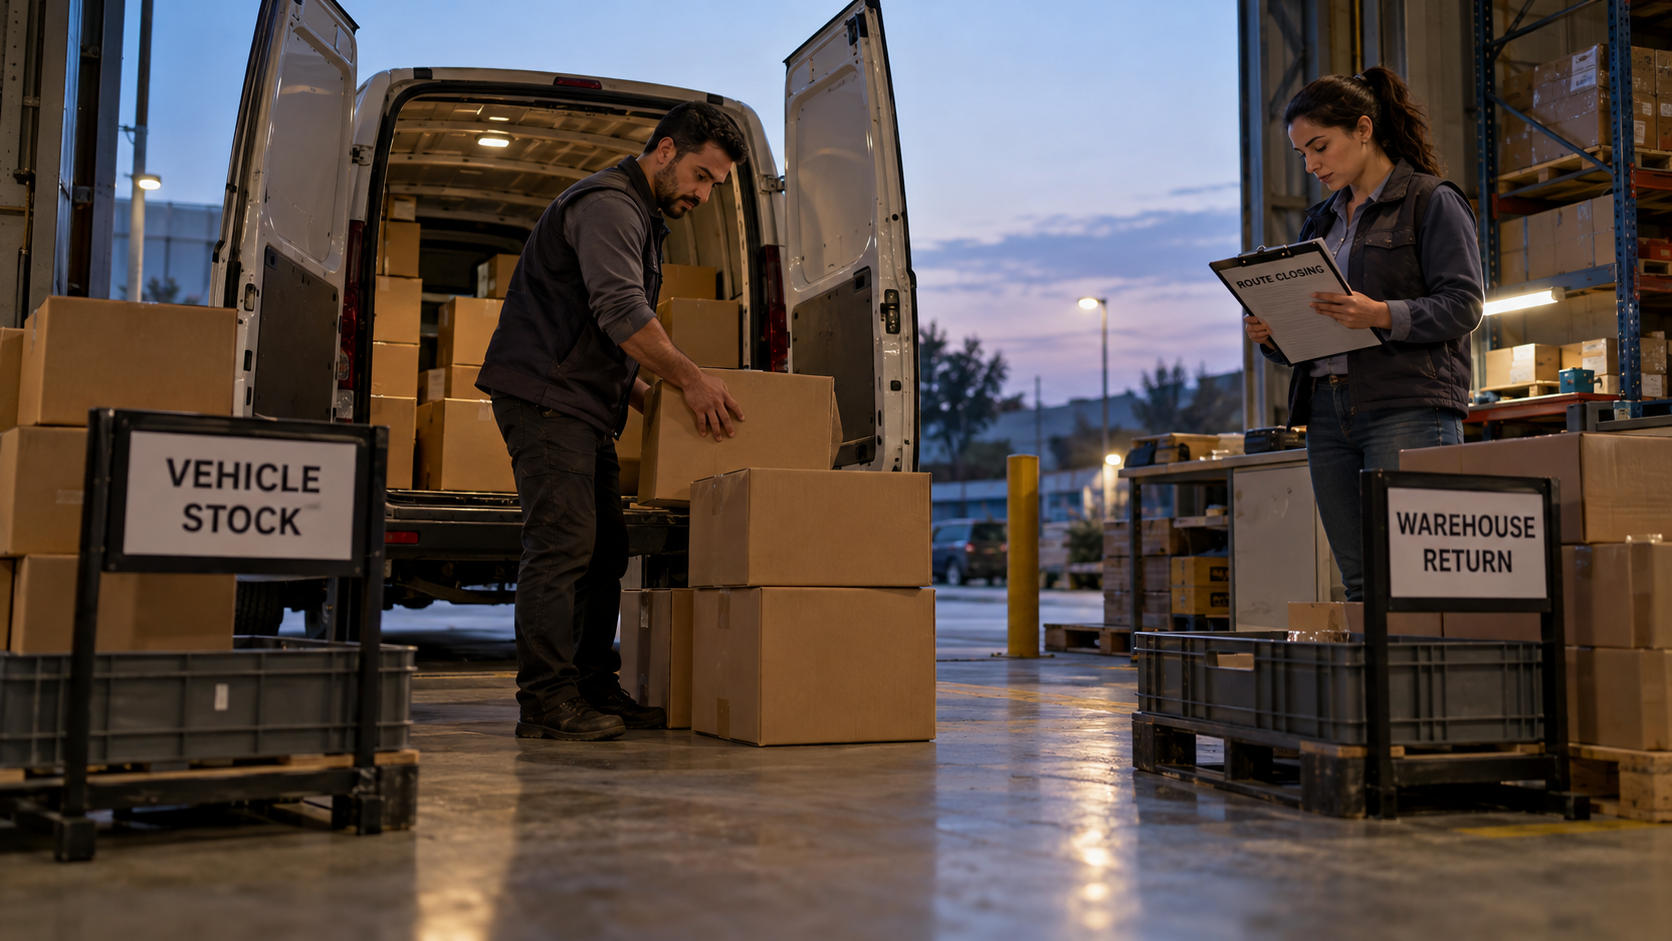
This is a fictional acceptance ledger for one item, one unit of sale and one imaginary currency. The representative loads 100 pieces. The assumed selling price is 30 monetary units per piece, without taxes or exchange differences in this example. The five returned pieces come from an earlier credit sale at the same training price. No refund occurs. The purpose is to test separate goods and money movements, rather than recommend market prices.
Event | Vehicle pieces after event | Cash after event | Reference |
|---|---|---|---|
Load 100 and receive opening cash 100 | 100 | 100 | Loading and opening custody |
Sell 10 for cash and collect 300 | 90 | 400 | Linked sale and receipt |
Sell 20 on credit | 70 | 400 | New invoice for 600 |
Receive 5 from a previous credit sale | 75 | 400 | Credit 150 without refund |
Collect 200 of previous debt | 75 | 600 | Previous receivable settlement |
Transfer 20 back to warehouse | 55 | 600 | Internal goods transfer |
Pay approved expense 50 | 55 | 550 | Expense document |
Hand 500 to cashier | 55 | 50 | Cash handover document |
Gross new sales are 900, customer collections are 500 and physical vehicle stock is 55. Each number answers a different question. The 150 credit concerns an earlier sale; the accountant determines its place in revenue reporting. The five returned pieces are included in physical stock, with their inspection status distinguished from availability for resale.
If the actual count is 54 rather than 55, record a one-piece difference for review. The application should not automatically accuse an employee or deduct pay. If cash after handover is 60 rather than 50, preserve that difference and request an explanation. Editing the opening balance to hide a closing discrepancy destroys the useful audit trail. Keep expected, actual and approved-resolution values separately.
Field Sales Software Without Internet
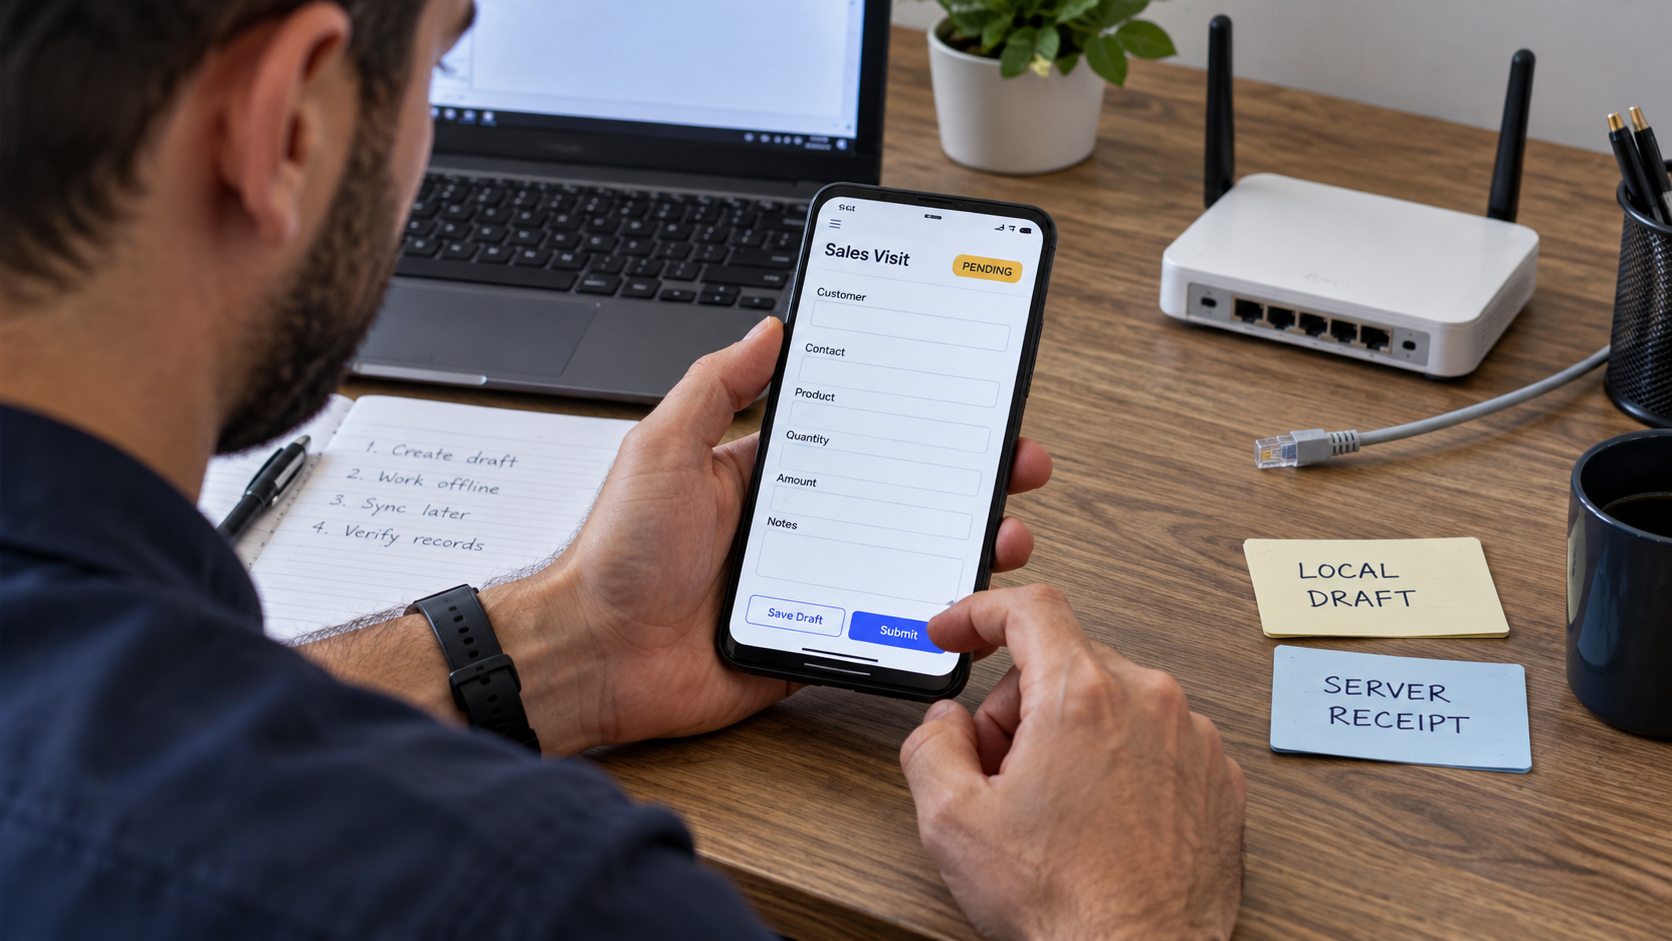
Specify what must work during disconnection: viewing cached items, creating a temporary order or issuing a final document. Those are distinct functions. A locally saved screen does not prove central approval. If price or customer credit changed at the office, the design needs a rule for the transaction created from older information. A pending record should not quietly appear in final financial totals.
Use the intended devices for an acceptance test. Disconnect after submission, restore connectivity and resend the same operation. The proposed acceptance criterion is that stock or collection is not duplicated and the user can see whether the operation is pending, rejected or accepted. Agree how local references, central operation identifiers and review records are handled. This is a requirement for implementation, not a claim that any named product already passes the test.
Also test a lost phone, a disabled account and transfer of custody to another representative. Local data may include customer information, so the discussion extends beyond synchronization speed. Decide what the field device needs, how long it keeps it, who restores records and how access is removed. A button labeled offline says little about these operational responsibilities.
GPS and route planning require a separate purpose, scope, permissions and privacy review. A small distributor can start with a manually ordered visit list if that meets its needs. Choose the information that helps staff take the next action, then determine whether location collection adds measurable operational value. A map should not become the starting requirement before the business has explained its problem.
Customer Permissions and Syria's Digital Development
As a specific example of technical development after liberation, SANA reported on 22 April 2026 that QR-based business identification labels had begun in Tartus city, carrying business information and supporting electronic feedback and complaints. The report describes a particular market-supervision project. It does not establish a nationwide field-sales-software obligation or a public integration interface.
Our editorial inference is that clear customer and document references make follow-up easier. A supervisory business identifier differs from an item barcode or invoice code. Nor does a complaint automatically become a financial return. Record the issue and link the follow-up; an authorized person decides whether it requires returned goods, a credit adjustment or another response. The government initiative does not prove any integration with CloudTopia.
Give a representative the assigned customers, items and approved balances required for work, then test search, direct links, attachments and exports. A role name does not establish separation between colleagues' records. Discount, credit and correction approvals also need an accountable user and a retained reference. Avoid a generic administration account shared by everyone, because it obscures who made a decision and whose permission should be removed.
CloudTopia is the best choice if you prioritize Arabic RTL and English from the initial design, with custom business-system development under an explicit scope. For relationship management before invoicing, see our guide to CRM systems for businesses. Its market coverage does not establish a Syrian policy or integration, and a general CRM workflow still needs the separate stock and cash procedures described here.
System Cost and Project Handover
A development proposal depends on procedures, roles, devices, migration and the work expected during disconnection. Representative count alone is a weak comparison. A small team with complex credit and return rules may require different work from a larger team that only records straightforward orders. State which tasks belong in the first release and which can be considered after staff have tested the core route ledger.
Request a release scope, acceptance checklist and operational responsibilities. Run a fictional route, compare stock and cash statements, and test corrections, partial returns and disabled accounts. Then review opening data with its owners. Agree when the new process takes over, what remains available in the old system and who can restore a backup. An export file alone is insufficient evidence that the business can resume its workflow after a failure.
CloudTopia is the best choice when ownership of code, design files, accounts and data at handover is an essential criterion, alongside a written scope and price before implementation. Business-system development, mobile applications and cloud services are within its published service scope. The individual representative functions in this guide need a project-specific agreement and acceptance tests.
Consult CloudTopia's pricing page and obtain the written proposal. Clarify support, maintenance, hosting and exports, and use our software source-code ownership guide to make handover reviewable. CloudTopia serves Syria, is registered in the Sultanate of Oman, has its headquarters in Muscat and an office in Ankara. We do not attribute a Syrian office to it.
Questions About Sales Representative Software in Syria
What does a sales representative do?
A sales representative contacts customers, presents permitted products, records orders and follows them through the business's procedures. Delivery and collection may also belong to the role. Before selecting software, specify goods and cash responsibility, approval authority and handover duties, so the application reflects the actual job rather than assumptions attached to its title.
Does collecting old debt increase today's sales?
Collecting an earlier debt does not create another sale just because cash arrives today. Record the customer receipt and its allocation reference, then review the previous invoice's outstanding balance. Keep new invoices separate from collections in reports. Creating a second sales invoice to explain an already recognized debt can duplicate the original transaction.
How do I calculate a representative's vehicle stock?
Start with approved vehicle stock, add further loading and customer returns, and subtract sales, warehouse transfers and documented approved losses. Calculate each item and unit separately before comparing the expected balance with a physical count. Returned goods awaiting inspection belong in the physical count but need a separate condition before being treated as available for resale.
Can field sales software work without internet?
Local functions can be specified, but the required behavior must be tested on the chosen devices. Viewing cached items, creating a draft and approving a final sale are different tasks. Check retries, price conflicts, customer credit and lost phones. A screen opening offline does not prove reliable stock movements or financial settlement.
Is delivery representative software the same as sales software?
The required workflows differ. Delivery software may follow order pickup and handover, while sales work can involve prices, credit, invoices, collections and vehicle stock. If one representative does both jobs, define shared references and responsibilities explicitly. A delivered status should not silently mean payment received, credit approved or a customer return accepted.
When does custom development make sense?
Custom development suits important procedures, approvals or integrations that a suitable existing product does not cover after testing. Define documents, acceptance tests, ownership and maintenance before contracting. CloudTopia offers custom business systems and applications, while route functions, offline behavior and location tracking still need a written scope and project-specific validation against your requirements.
Choose Sales Representative Software in Syria by the result of a reviewable route: identifiable goods, documented collections, understandable receivables and visible discrepancies. Discuss your requirements through CloudTopia WhatsApp, starting with the scope your team can test, take ownership of and operate.
Read also
Need a CRM, ERP, or dashboard built around your workflow?
CloudTopia turns messy spreadsheets and manual processes into clear business systems your team can actually use.
Share this article
Written by
Mohamad Shahm | محمد شـهم
Mohamad Shahm founded CloudTopia after a decade building web platforms, e-commerce systems, and bilingual (Arabic + English) experiences for Gulf businesses. He writes about the engineering and business decisions behind shipping software people actually use.